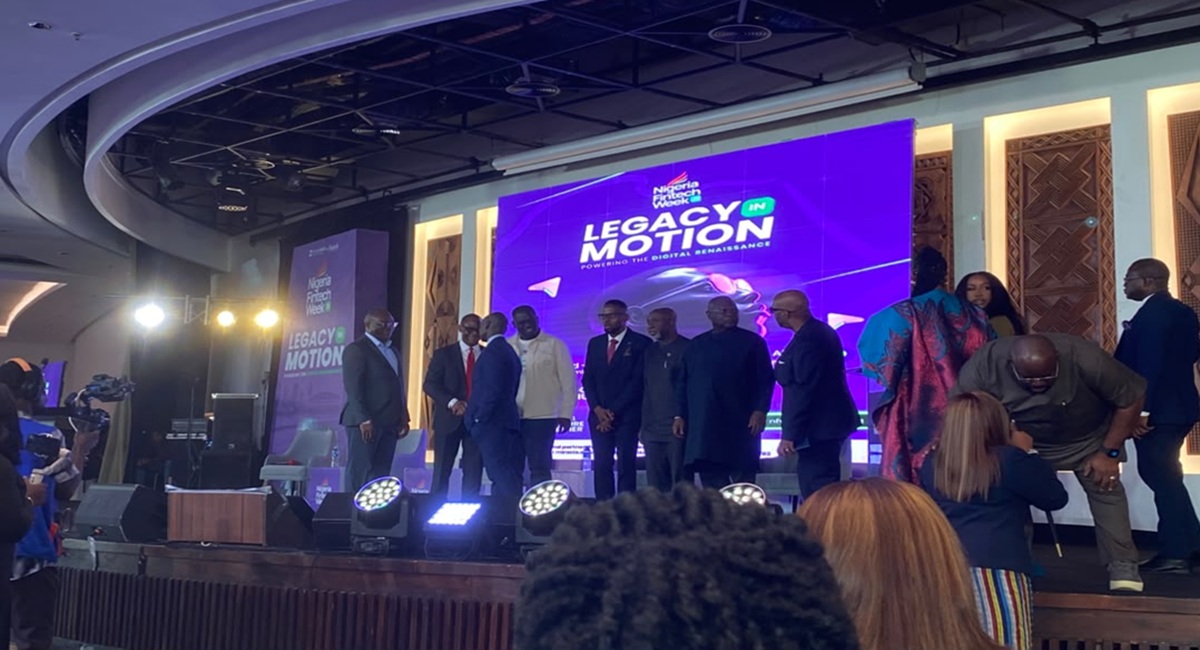
Nigeria Fintech Week 2026 opened in Lagos this week with a noticeably different tone from past editions. Instead of debating whether Nigerians trust digital payments, speakers spent the day discussing what the industry should build now that billions of transactions already move through digital channels every year.
How far payments have already come
Dr Stanley Jacob, President of the Fintech Association of Nigeria and chief host of the event, opened by noting how the public conversation around fintech has shifted from basic curiosity to questions about monetisation. He pointed out that transactions on the NIBSS Instant Payment platform jumped from about 1.5 billion in 2022 to nearly 11 billion in 2024, a scale of growth that has changed what the industry now needs to focus on.
Jacob identified four priority areas for the sector going forward: stronger digital infrastructure, responsible use of AI at scale, closing the financial inclusion gap, and making it easier for fintech companies to operate across African borders.
Pushing Nigerian fintech beyond Nigeria
Dr Segun Aina, President of the Africa Fintech Network and chairman of FintechNGR’s board of trustees, used his remarks to argue that Nigerian companies are thinking too small. He noted that the Africa Fintech Network, launched in Lagos in 2018 with participants from about five countries, now covers more than 44 African markets. His argument was straightforward: Nigeria’s 240 million people are a fraction of Africa’s 1.4 billion population.
Aina acknowledged that expanding across African borders is difficult in practice, since each country tends to have its own licensing rules, compliance requirements and approval processes. He said the Africa Fintech Network is working with partners including Afreximbank on a Fintech License Passporting Initiative, intended to make it easier for properly regulated fintech companies to expand into new markets without restarting the licensing process from scratch each time. He was careful to frame the effort as easing friction rather than lowering regulatory standards, and called for banks and fintechs to work together rather than compete.
CBN repeats its call for coordinated regulation
Representing the Central Bank of Nigeria, Mr Abiodun Okunola reiterated the four barriers he said are slowing the industry: fragmented regulation, weak public trust, exclusion of underserved groups, and fear of innovation within the regulatory system itself. He called for closer coordination between fintechs, banks and regulators, and argued that oversight should focus on removing unnecessary friction rather than slowing innovation down. He flagged AI, embedded finance, open banking and cross-border payments as the areas regulators will need to keep pace with in the coming year.
Washington weighs in on Nigeria’s fintech exports
The U.S. Consul General in Lagos, Brandon Hudspeth, used his remarks to highlight the depth of commercial ties between Nigeria and the United States. He noted that Nigeria now has roughly 430 fintech companies, citing Flutterwave, Paystack and Moove as examples of firms that built products locally before expanding internationally. He added that American investors supplied about 60 percent of venture capital equity funding into Nigeria’s wider tech ecosystem between 2015 and 2025, a figure he put at roughly 5 billion dollars, and said the U.S. wants to deepen trade ties with technology and finance at the centre of that relationship.
What it adds up to
Taken together, the opening day’s talking points pointed to a shift in what Nigeria’s fintech industry sees as unfinished business. The infrastructure for moving money has largely been built. The conversations this week focused instead on regulatory coordination, responsible AI adoption, closing gaps in financial inclusion, and turning Nigerian-built fintech products into exports across the rest of the continent.