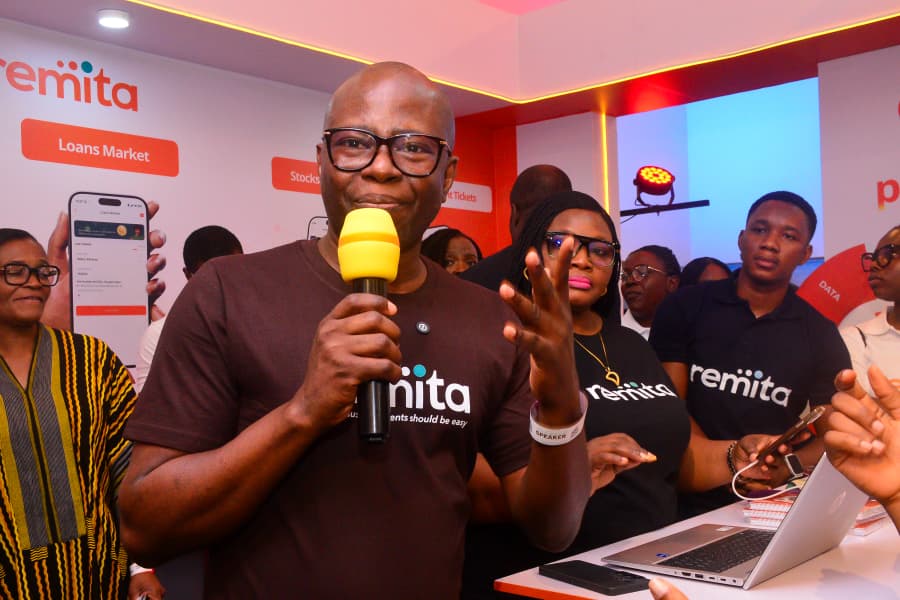
Remita has stepped into the consumer fintech space with a new mobile app that lets users manage multiple bank accounts, transfer money across African countries, and access several other financial services from one platform. The app was unveiled this week in Lagos during Nigeria Fintech Week, marking Remita’s shift from a background payments infrastructure provider into a direct-to-consumer product.
What The New App Does
The Remita mobile app allows users to view and manage balances across several bank accounts from a single screen, regardless of which banks they use. Beyond basic transfers and bill payments, the app also supports recurring payments, loan comparisons, stock and share investments, flight and event ticket bookings, and micro-pension access. The company is positioning it as a full financial management tool rather than just another transfer app.
Cross-Border Transfers Are A Major Feature
One of the app’s headline features is its cross-border payment capability. Remita is working with the Pan-African Payment and Settlement System to let users send money directly from their local bank accounts to recipients in other African countries. According to the company’s managing director, users will be able to debit any of their linked local bank accounts and transfer funds to bank accounts across the continent, all from within the app. This positions Remita to compete directly with existing cross-border payment platforms as African fintechs push harder into intra-continental transfers.
Why This Matters For Remita
For two decades, Remita has largely operated as infrastructure that individuals interacted with indirectly, mostly through organisations, schools, and government platforms processing payments in the background. This launch changes that. The company is now asking everyday Nigerians to open and use a Remita-branded app directly, competing in a market already crowded with digital banks and fintech wallets offering similar transfer, savings, and bill payment features.
A Tougher Market Than Enterprise Payments
The consumer fintech space in Nigeria is significantly more competitive than the enterprise infrastructure space Remita built its name in. Nigerians already have several options for transfers, savings, loans, and investments, so Remita’s success will likely depend on how well it can differentiate itself. Its strongest selling point may be integration: giving users a single, reliable view of accounts spread across different banks, something most single-bank apps cannot offer. If the multi-bank and cross-border features work as promised, Remita could turn its two decades of payments experience into a genuine consumer advantage rather than just another wallet app.
What To Watch Next
For now, only Nigerian bank accounts can be registered on the app, even though outbound transfers can reach recipients across Africa. It remains to be seen how quickly the cross-border transfer feature scales beyond the initial rollout, and how competitively Remita prices these transactions compared to existing options. Adoption will also depend on how smoothly the multi-bank linking process works in practice, since asking users to connect several bank accounts to one app raises the usual questions around trust and data security.
Remita’s move signals a broader trend among Nigerian payment infrastructure companies looking to capture more value by going direct to consumers, rather than staying behind the scenes.