A milestone for PAYG credit in Kenya
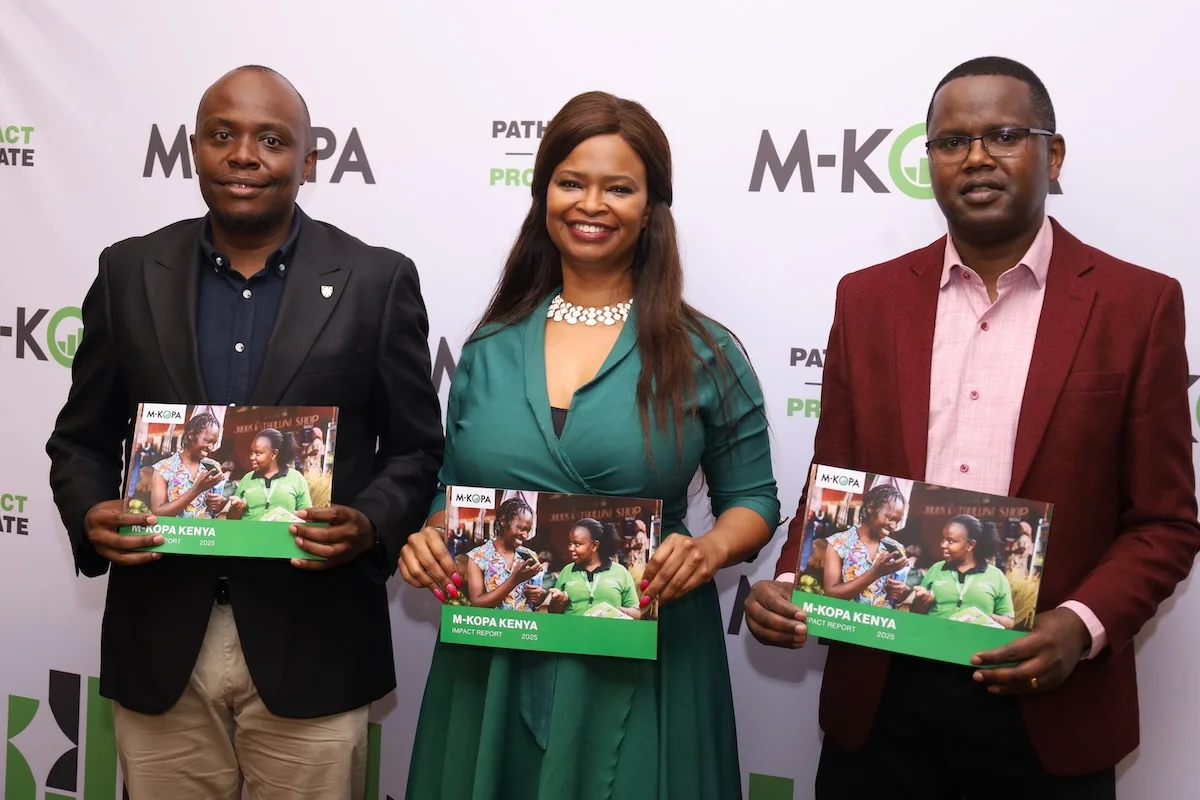
M-KOPA has announced that it has unlocked KES 207 billion in cumulative credit for customers in Kenya since launching in 2010. The figure reflects the total value of asset-financing and digital-credit facilities issued through its platform, which combines mobile payments, device-locking technology and behavioural credit assessment.
The company says more than 4.8 million customers in Kenya have accessed smartphones, solar home systems, e-mobility products and short-term digital loans through its pay-as-you-go model. The update follows M-KOPA’s 2024 results, where the company reported its first-ever profit of KES 1.2 billion, marking a shift in the scale and sustainability of its credit operations.
Technology reshaping financial access
M-KOPA’s credit model shows how technology can reach people excluded from traditional banking systems. Customers typically make a deposit and repay in small daily or weekly instalments. Over time, these repayments form a digital credit history.
The system relies on device telemetry, automated repayment tracking and tight integration with mobile money. This allows M-KOPA to manage risk at scale and expand into new asset categories, including electric motorcycles and higher-end smartphones.
It is important to note that the KES 207 billion figure represents cumulative credit issued, not the size of the current loan book. Even so, it illustrates the growing role of asset financing and digital lending in markets where formal credit penetration remains low.
For fintech observers, the company’s progress is a signal that hybrid hardware-plus-credit models can be viable in emerging markets. Profitability suggests its risk algorithms and repayment structures have matured, though questions remain around non-performing loans and expansion into new geographies.
The customers and industries that rely on M-KOPA
Low-income and underbanked consumers in Kenya remain the core beneficiaries. They gain access to smartphones, solar energy and mobility tools through small-ticket credit that would otherwise be out of reach. Telecom partners, device manufacturers and e-mobility companies also depend on M-KOPA’s financing rails to reach mass-market customers.
Financial-services regulators and lenders are watching closely. Models like M-KOPA’s influence how credit risk, digital-identity data and collateral mechanisms evolve across the region.
What to expect next
M-KOPA is expected to deepen its product lines, extend its digital-loan offerings and push further into e-mobility and smartphone financing. Regional expansion beyond Kenya will depend on regulatory approvals, currency conditions and repayment behaviour in new markets.
Analysts will track how much of the KES 207 billion in cumulative credit translates into customer retention, device upgrades and long-term financial-inclusion outcomes.