
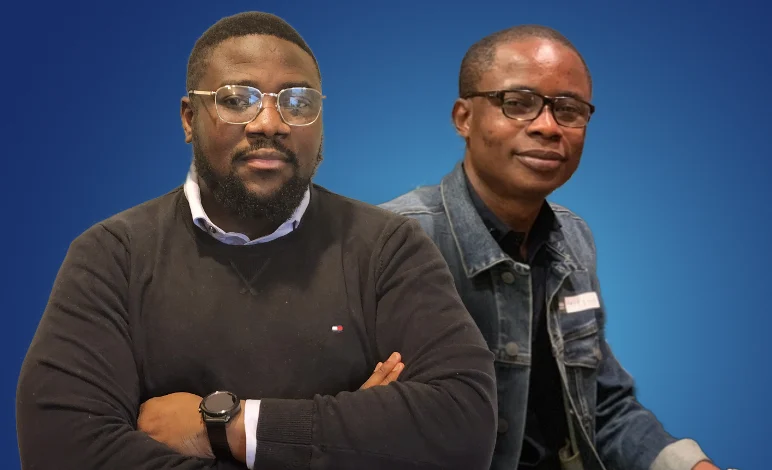
The closure, announced by co-founders Celestine Omin and Olufunbi Falayi on October 25, 2026, follows unsuccessful efforts to raise debt financing, lengthy banking integrations, and an acquisition offer that the founders ultimately rejected.
Founded in 2021, Klump developed technology that allowed Nigerian consumers to purchase goods immediately and spread payments over instalments. Its platform served thousands of customers and hundreds of merchants, helping businesses offer credit directly at checkout.
However, the startup struggled to build a sustainable business around its lending infrastructure, with the founders acknowledging that dependence on external financial institutions limited its ability to scale.
Why Klump Is Shutting Down After Five Years
Klump initially operated its own loan book, allowing the company to make credit decisions quickly and finance purchases that traditional lenders might consider too risky.
The model enabled the startup to offer credit decisions in under five minutes, eliminating the lengthy approval processes associated with conventional consumer loans.
But maintaining and expanding its lending operations required substantial capital.
When Klump attempted to raise debt financing to support its next phase of growth, it failed to secure the amount needed.
The company subsequently changed its business model, becoming a technology platform connecting consumers with commercial banks, microfinance banks and other lending institutions.
Under the arrangement, customers shopping on supported e-commerce platforms could select Klump at checkout, compare available financing options and receive credit decisions from participating lenders.
Klump provided the technology, while financial institutions funded the loans and assumed the credit risk.
Although the model reduced Klump’s need to finance purchases directly, it introduced another challenge: dependence on the operational processes and lending decisions of its banking partners.
According to the founders, integrating individual financial institutions typically took between six and 18 months, with some partnerships requiring nearly three years of commercial, legal and technical negotiations.
Banks also maintained different lending limits, sector restrictions and risk requirements, limiting the range of financing Klump could offer.
These constraints slowed the company’s expansion even as it continued bearing operating costs.
The founders acknowledged that regaining control over the speed of lending decisions would have required access to sufficient capital and an independent loan book, neither of which the business was able to secure.
Klump’s $1.2 Million Funding and Acquisition Attempts
Klump attracted investor interest early in its operations.
In March 2022, the company secured a $780,000 pre-seed funding round led by Seedcamp, with participation from Magic Fund, Voltron Capital, Yellowwood and other investors.
The startup subsequently raised additional financing, bringing its total funding to approximately $1.2 million across two rounds, according to its founders.
Despite the investment, Klump struggled to secure the lending capital necessary to expand its original business model.
The company also explored acquisition opportunities as an alternative to raising more funding.
Its first acquisition discussions began in the fourth quarter of 2023 but ended without an agreement after months of due diligence.
At the beginning of 2026, Klump again considered whether to raise additional capital or pursue an acquisition.
The founders ultimately decided that BNPL technology might be more sustainable as part of a larger financial services company than as a standalone business.
They held discussions with several fintech companies and eventually received an acquisition offer.
However, the offer was rejected. The founders did not disclose the potential buyer, the proposed transaction value or why they declined the deal.
Unable to secure a viable path forward, Klump decided to shut down.
Major Partnerships Were Not Enough to Save Klump
Klump’s closure comes just months after it expanded its presence across Nigeria’s e-commerce market.
In July 2026, Techsoma reported that Konga had integrated Klump’s BNPL technology, allowing customers to purchase products by paying a portion upfront and spreading the remaining amount across instalments.
The startup also partnered with Jumia, extending its payment technology to two of Nigeria’s largest online shopping platforms.
Other merchants and partners included iStore and SLOT, while lending relationships involved institutions such as FirstBank, Wema Bank, Stanbic IBTC, Fidelity Bank and Credit Direct.
According to its founders, Klump’s technology helped some merchants reduce abandoned shopping carts by as much as 45%, although the figure has not been independently verified.
The company also developed Klump Commerce, an online marketplace designed to help smaller businesses offer instalment payments without building their own e-commerce websites.
Despite these commercial relationships and reported customer traction, the business could not overcome the financing and operational challenges affecting its growth.
What Klump’s Shutdown Means for Nigeria’s Fintech Industry
Klump’s closure highlights a difficult challenge in Nigeria’s growing consumer-credit market: building technology that connects borrowers with lenders does not necessarily give a startup control over the capital or lending decisions required to scale.
While partnerships with established financial institutions can reduce the risks associated with lending directly, they can also introduce lengthy integration processes and limits on the products a fintech can offer.
For Nigerian startups operating in embedded finance and consumer lending, Klump’s experience demonstrates how commercial distribution, investor backing and a functioning product may still be insufficient without sustainable access to financing.
The shutdown also raises questions about how existing merchants and customers will transition away from the platform.
The founders’ announcement did not specify how outstanding transactions, existing repayment obligations or merchant integrations would be handled.
For now, Klump’s closure marks the end of a five-year attempt to make consumer credit more accessible at the point of purchase.
Despite the decision to shut down, its founders maintain that the problem they set out to solve remains.
“Access to credit remains an unsolved problem,” they wrote in their farewell statement.
Klump’s experience suggests that solving it will require more than faster checkout technology. It will also depend on whether fintech companies can secure reliable lending capital and build partnerships that support sustainable growth.