
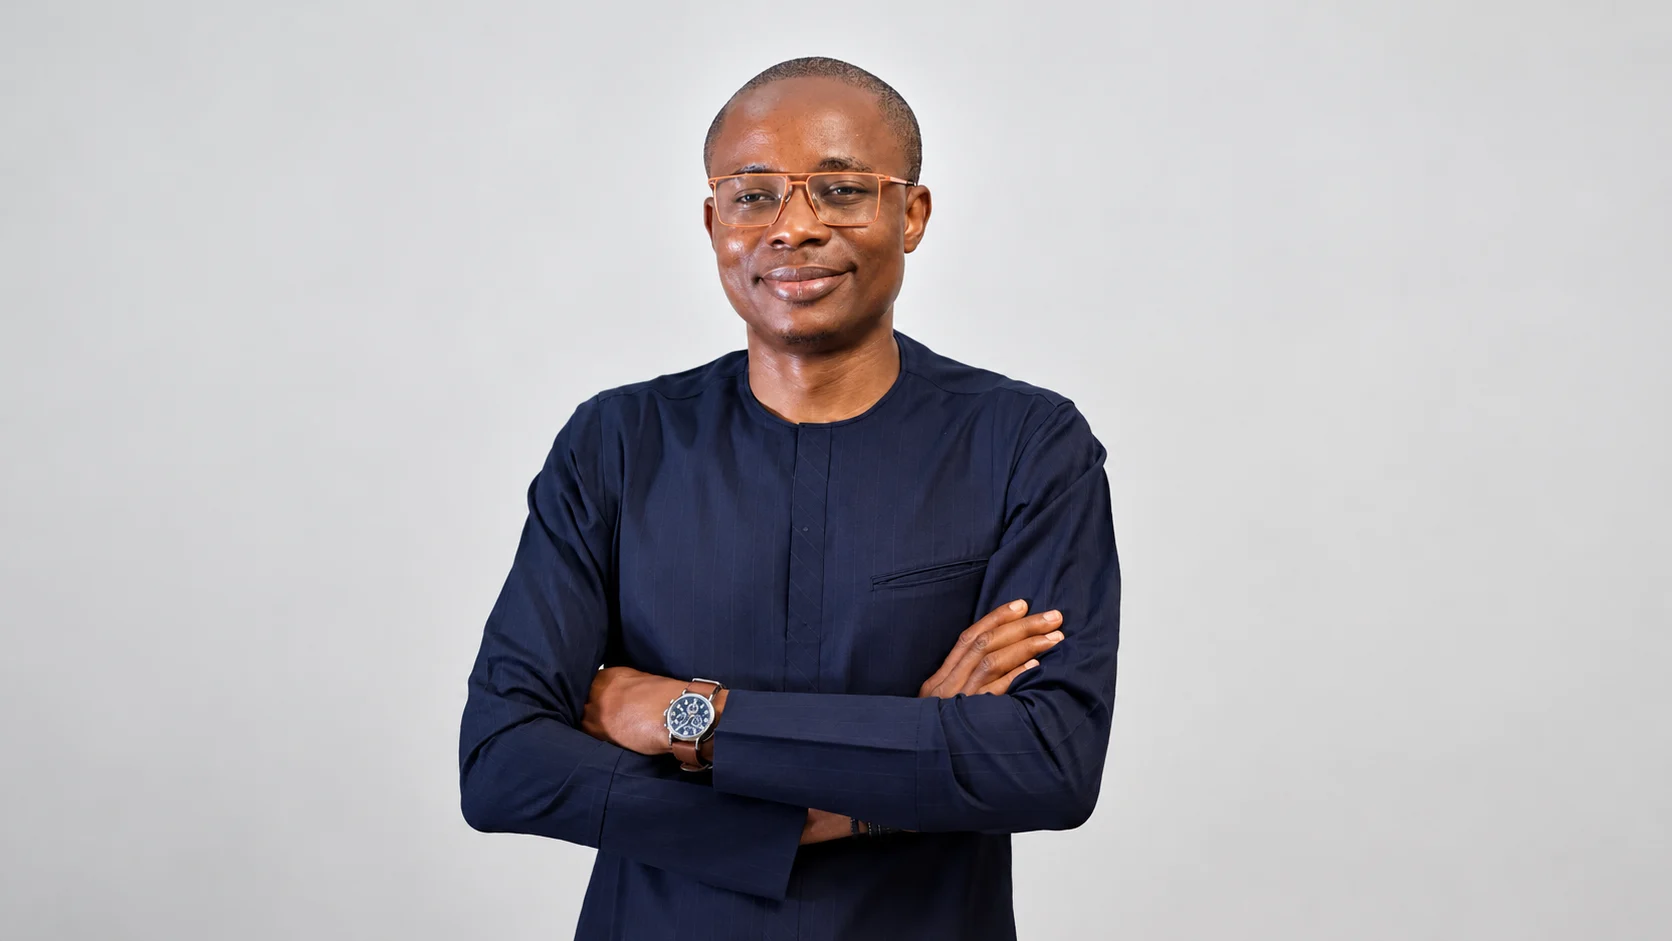
If you have ever worked with Celestine Omin, you will know that he is one of the most hardworking, technically gifted and relentlessly curious people you will encounter in Africa’s technology ecosystem.
He is the kind of engineer who does not simply see a problem and talk about it. He wants to understand it, take it apart and build something that solves it. His journey, from his engineering career to co-founding Klump alongside Olufunbi Falayi, has reflected that philosophy.
So when Celestine announced on 25 October 2026 that Klump was shutting down after five years, I found myself thinking less about another Nigerian startup closing its doors and more about what happens when exceptionally talented founders build a genuinely useful product but cannot overcome the structural realities of the market in which they operate.
Because if there is one thing Klump’s story demonstrates, it is that building a great product and building a sustainable business are two very different things.
And sometimes, even getting both reasonably right is not enough.
Klump Was Solving a Real Problem
When Klump launched five years ago, the proposition was straightforward. Nigerians should be able to purchase goods and services and spread their payments over time without enduring the lengthy approval processes associated with traditional lending.
The ambition was to make credit decisions in under five minutes.
For anyone familiar with Nigeria’s consumer lending environment, this was an important proposition. Access to credit remains difficult for millions of people, and the gap between wanting to purchase something and being able to afford it immediately creates a significant opportunity for retailers and financial institutions.
Klump built technology to bridge that gap.
Over five years, the company worked with hundreds of merchants, including Jumia and Konga, and served thousands of customers. According to its founders, its technology helped merchants reduce cart abandonment by as much as 45%.
It also developed Klump Commerce, which allowed merchants without sophisticated e-commerce infrastructure to sell online and offer instalment payments.
Imagine a phone retailer in Computer Village selling to a customer in Calabar, with financing arranged at checkout. That was the kind of commerce Klump wanted to enable.
The problem was real. The product worked. The merchants were there.
So what went wrong?
The Problem With Building a Business Around Other People’s Decisions
This is where Celestine’s account becomes particularly interesting.
Klump initially operated its own loan book, allowing it to make underwriting decisions quickly and finance transactions that traditional lenders might reject.
But lending requires capital, particularly when the objective is to scale.
The company attempted to raise debt financing to support its growth. That effort did not produce the capital it needed.
Consequently, Klump changed its model.
Rather than lend directly, it would become the technology connecting merchants, customers and financial institutions. Banks and other lenders would provide the money, while Klump supplied the infrastructure to make lending possible at checkout.
On paper, it was an intelligent pivot.
Banks needed to lend. Merchants needed customers to complete purchases. Customers needed flexible payment options.
Klump could connect all three without carrying the credit risk itself.
But there was a fundamental weakness in this model: Klump no longer controlled the most important part of its customer experience.
A bank could take six months, a year or even longer to complete an integration. Some partnerships reportedly stretched towards three years.
Even after integration, lenders could restrict the sectors they financed, limit transaction sizes or change their appetite for risk.
Meanwhile, Klump still had employees to pay, technology to maintain and a business to operate.
This is one of the most important lessons in the entire story.
*You can build technology that operates in five minutes and still have a business that moves at the speed of a bank’s legal department.*
And when your competitive advantage is speed, that contradiction can become fatal.
Nigeria’s Fintech Ecosystem Has an Infrastructure Problem That Technology Alone Cannot Solve
We often celebrate African fintech companies for the speed at which they build products, raise capital and acquire users.
We spend considerably less time discussing the institutional infrastructure those products depend on.
A startup might have an excellent engineering team, a working product and willing customers, but if its commercial model requires multiple banks to approve integrations, update internal systems, satisfy compliance requirements and align their risk policies, its ability to scale becomes dependent on institutions operating under completely different incentives.
Celestine’s account reveals that Klump sometimes had to help banks design the very third-party consumer lending APIs required to make the partnerships work.
Think about that.
A startup trying to scale its own business was simultaneously helping established financial institutions build the infrastructure necessary to support that business.
There is value in that work, certainly. But who ultimately captures the value?
The banks retain their customers, capital and lending infrastructure. The merchants retain their distribution. The startup must find a way to earn enough from facilitating transactions to justify years of development and integration.
Without sufficient transaction volume, the economics become extremely difficult.
This is not an argument that banks are deliberately frustrating innovation. Financial institutions have legitimate regulatory, compliance and risk-management obligations.
It is an argument that the commercial realities of building financial infrastructure in Nigeria are frequently more complicated than the excitement surrounding fintech suggests.
The $1.2 Million Question
Klump raised approximately $1.2 million across a seed round and an extension, attracting investors including Seedcamp, Magic Fund, Voltron Capital and several prominent angel investors.
For a startup operating across financial technology, credit infrastructure, merchant acquisition and institutional partnerships, $1.2 million is not an enormous amount of capital over five years.
Yet the company managed to build integrations with major e-commerce platforms and work with financial institutions including First Bank, Stanbic IBTC, Wema Bank, Fidelity Bank and others.
That deserves recognition.
But it also raises an uncomfortable question about how we evaluate startup performance.
We have become accustomed to judging founders by how much money they raise, how quickly they expand and the valuations attached to their businesses.
Perhaps we should spend more time examining how much meaningful infrastructure they build, what they learn about the markets they serve and whether their business models can survive without another funding round.
Klump appears to have been disciplined with capital, according to its founders. But capital discipline alone cannot compensate for a model in which revenue growth is constrained by dependencies outside the company’s control.
There is also a difference between attracting investors who believe in your vision and securing the specific type of financing your business needs.
Klump had equity backing. What its original model needed to scale was substantial lending capital.
Those are not interchangeable.
Could an Acquisition Have Saved Klump?
Perhaps the most revealing part of the announcement concerns the company’s attempts to find a buyer.
Klump first attracted acquisition interest in the final quarter of 2023, but discussions collapsed following due diligence and disagreements over alignment.
By early 2026, the founders were considering whether to raise additional capital or pursue an acquisition.
They chose the latter.
Their reasoning was significant: Buy Now, Pay Later might work better as a feature within a larger financial services ecosystem than as an independent company.
I think this is an important observation, particularly for founders building products that sit between customers and established financial institutions.
Not every valuable technology needs to exist as a standalone company.
Sometimes the most commercially viable future for a product is to become part of a bank, payments platform, marketplace or broader financial services business that already possesses the distribution, balance sheet and customer relationships required to scale it.
Klump held discussions with several fintech companies and received an offer, which it declined.
We do not know the financial or commercial terms of that offer, so it would be unfair to suggest that rejecting it was a mistake.
But the broader lesson is worth considering.
An acquisition is not necessarily a failure of entrepreneurial ambition. In some circumstances, it may be the most effective way to preserve the value of what has been built.
What Founders Should Take Away From Klump
There are several lessons here, but three stand out to me.
First, distribution is just as important as technology. Building something people need is only the beginning. The ability to reach those customers consistently, convert demand into revenue and retain sufficient control over the process is what makes a business sustainable.
Second, understand which dependencies can destroy your business. Partnerships are valuable, but when your entire growth strategy depends on another organisation’s willingness or ability to act, you have introduced a risk that even the best engineering team may be unable to solve.
Third, raising capital is not the same as solving your capital problem. Different business models require different types of funding. A lending business needs access to lending capital. A technology infrastructure company needs sufficient revenue and commercial scale to sustain its operations. Confusing the two can create problems that become increasingly difficult to resolve.
There is another lesson, although founders rarely discuss it openly.
Knowing when to stop is also a business decision.
We celebrate persistence, and rightly so. But persistence cannot mean continuing indefinitely simply because you have already invested five years of your life into something.
Sometimes the responsible decision is to acknowledge that the economics are not working, that the acquisition opportunities have not materialised and that the business cannot continue on its existing terms.
That decision does not erase the work that came before it.
The End of Klump Is Not the End of Its Contribution
One thing I particularly appreciated about Celestine and Olufunbi’s announcement was its transparency.
They explained the original model, why they pivoted, the difficulties with institutional partnerships, the unsuccessful debt raise and the acquisition discussions that ultimately did not produce an outcome.
There was no attempt to disguise the closure with vague language about strategic restructuring or a new chapter.
They built a company. It achieved meaningful things. They encountered obstacles they could not overcome. And now they are closing it.
Africa’s startup ecosystem needs more accounts like this.
For every company that raises a significant funding round or announces an impressive valuation, there are founders quietly navigating difficult commercial decisions that rarely become conference presentations or celebratory LinkedIn posts.
Yet those experiences contain some of the most valuable lessons about building businesses on the continent.
Klump helped merchants sell, customers access credit and financial institutions develop capabilities they might otherwise have taken longer to build.
Those contributions remain, even if the company does not.
And for Celestine Omin and Olufunbi Falayi, five years of building Klump represent experience that cannot be replicated in a classroom, accelerator programme or venture capital pitch session.
I would not pretend to know what either founder will do next. But I would be surprised if this is the last significant contribution we see from them.
The closure of Klump is disappointing, particularly because the problem it set out to solve remains largely unresolved.
But perhaps the most important thing about this story is that it challenges a convenient assumption in our technology ecosystem: that talented founders, good products and committed investors will inevitably produce successful companies.
They will not.
Markets are complicated. Capital has limitations. Institutions move slowly. Business models evolve. And sometimes the conditions necessary for a company to succeed simply do not come together.
Klump’s five-year journey is not proof that Buy Now, Pay Later cannot work in Nigeria. It is evidence of how difficult it can be to make it work independently, without control over the capital, distribution and lending decisions on which the model depends.
That is a lesson worth considerably more than another startup success story.
And it is why Celestine and Olufunbi’s decision to share the details of their journey matters.
The company may have reached the end of the road, but the knowledge it leaves behind should help other founders travel further.